Alert 08.27.26
Alert
SEC Innovation Exemption for Tokenized NMS Stock
Takeaways
09.29.26
The Securities and Exchange Commission (Commission) has created a temporary, conditional pathway for a specific type of on-chain secondary market in tokenized public stocks. The five-year Order permits qualifying Tokenized Securities Venues (TSVs) to operate permissioned automated market maker (AMM) liquidity pools for tokenized National Market System (NMS) stock without registering as national securities exchanges or as broker-dealers and without operating as alternative trading systems (ATSs). It also provides limited dealer relief for certain firms that supply proprietary liquidity to those pools.
Overview
The Order is effective from September 17, 2026, through September 17, 2031, unless modified earlier by the Commission. Unlike the staff statements that preceded it, the Innovation Exemption is formal Commission action under Section 36 of the Exchange Act. The Commission describes the exemption as an interim measure intended to permit market activity, generate observable data, and inform more durable rulemaking.
At a high level, a TSV is an organization or group that provides one or more AMM liquidity pools and determines who may access them. Participants trade against pooled liquidity rather than through a conventional order book. Access to trading on a TSV is permissioned, while the smart contracts must be public and auditable and deployed on a public, permissionless blockchain.
The scope of eligible securities and transactions is similarly limited. The exemption covers secondary trading in Tokenized NMS Stock, whether tokenized by the issuer or by an unaffiliated third party. Every trading pair must include Tokenized NMS Stock. Third-party synthetic products are outside the exemption, as are primary offerings. Where an unaffiliated third party tokenizes an issuer’s stock, the issuer must receive advance notice and an opportunity to object to use of the exemption for that stock.
Although a TSV would be exempt from exchange registration, the TSV is subject to substantial public disclosure, transaction data, recordkeeping, operational, and market oversight requirements, as well as limits on the number of stocks and trading volume permitted in the pilot. A separate, narrower exemption addresses dealer status for certain proprietary liquidity providers.
Background and Regulatory Context
The Innovation Exemption may be best understood as one step in a broader SEC effort to develop a regulatory framework for tokenized securities and on-chain markets. Since early 2025, the Commission has considered and pursued a series of related initiatives addressing crypto market structure and token taxonomy, tokenized securities, user interfaces, transfer agents, coordination with the CFTC, and the use of exemptive relief to permit new market models while more durable rules are developed. The Order builds on those initiatives in a controlled framework, focused on one category of securities, one trading architecture, and targeted exchange and dealer relief, rather than the broader regulatory sandbox that some market participants had anticipated based on earlier remarks.
Two days before the Order was issued, the Senate rejected cloture on the motion to proceed to the CLARITY Act. In announcing the Order, Chairman Atkins described the SEC as taking a significant step forward “within its statutory authority.” The timing underscores an important feature of the present regulatory landscape: Federal agencies are moving forward where they believe their existing statutes permit them to do so, but some elements of a comprehensive digital asset market structure will remain dependent on Congressional action.
For example, Michael Selig, chairman of the Commodity Futures Trading Commission (CFTC), has directed CFTC staff to explore rules establishing a crypto-asset market structure under the agency’s existing authority, including a framework under which registered and currently unregistered crypto exchanges could seek designation as a type of designated contract market and offer leveraged or margined crypto-asset trading. At the same time, he has emphasized that legislation remains important to establish durable jurisdictional lines and statutory core principles for crypto-asset spot markets. According to a press report, a White House official made a related point: Without Congressional action, the CFTC lacks comprehensive regulatory authority over spot markets for non-security crypto assets, limiting its ability to establish a complete federal regulatory framework for those markets.
For a table that highlights the principal SEC and related federal regulatory developments that have shaped the emerging framework for tokenized securities and the market infrastructure for trading them, click here.
Detailed Provisions of the Order
The Order creates two related exemptions. The principal exemption permits a qualifying TSV to operate AMM liquidity pools for Tokenized NMS Stock without registering as a national securities exchange or registering as a dealer and without operating as an ATS. A separate exemption provides limited dealer relief for certain firms providing proprietary liquidity to those pools. Both exemptions are temporary and subject to extensive conditions intended to keep the experiment limited, transparent, and subject to Commission oversight.
The TSV and the Exchange Exemption
A TSV is defined functionally as an organization, association, or group of persons that both provides one or more AMM liquidity pools through which permissioned participants may interact and agree to trade terms and establishes the standards governing access to those pools. The definition can therefore encompass a single entity or a group performing different components of the venue function.
A qualifying TSV is exempt from the Exchange Act definition of “exchange.” For its covered activities, it therefore need not register as a national securities exchange or as a dealer and need not operate as an ATS. It also is not treated as a “trading center” or “market center” under Regulation NMS, and thus the rules under Regulation NMS applicable to exchanges, ATSs, trading centers and market centers do not apply. The exemption allows the Commission to test an AMM-based market structure without requiring it to conform to all the rules developed for conventional exchange and order book markets.
Importantly, the Innovation Exemption continues to require compliance with sanctions administered by the Office of Foreign Assets Control (OFAC) and applicable anti-money laundering (AML) requirements, among other laws. Specifically, the TSV must be a U.S. person, which includes any U.S. citizen, permanent resident alien, entity organized under U.S. laws, or any person in the United States. As a U.S. person, the TSV must comply with economic and trade sanctions programs administered by OFAC, including prohibitions on transacting with persons on the SDN List. No organization, association, or person within a group comprising the TSV may be subject to an unpermitted statutory disqualification (i.e., a statutory disqualification for which permission to continue has not been granted by the Commission or the relevant SRO). A registered entity may participate in a TSV structure, but its registered activities remain subject to otherwise applicable requirements and must be kept separate from the TSV activity. The TSV also must also disclose its procedures for verifying participant identities, “including for compliance with … applicable AML/CTF requirements.”
Reliance on the exemption does not require an SEC application or affirmative approval. At least 30 calendar days before beginning operations, the TSV must publish a detailed public Notice and notify the Commission within one business day. The TSV must thereafter update the Notice as specified events and changes occur.
What Can Trade
The exemption is limited to Tokenized NMS Stock. This includes NMS stock tokenized by or on behalf of its issuer and NMS stock tokenized by an unaffiliated third party. It does not include a third-party security that merely provides synthetic exposure to the referenced stock, such as a linked security or security-based swap, and the Order separately excludes rights and warrants.
The relief applies only to secondary trading. A TSV may not conduct a primary issuance or initial offering under the TSV Exemption. All offers and sales of Tokenized NMS Stock must still be registered under the Securities Act or conducted pursuant to an exemption from its registration requirements. Tokenization does not alter the application of the Securities Act or other requirements governing the issuance or resale of securities.
Every trading pair must include at least one Tokenized NMS Stock. Each other leg may be another Tokenized NMS Stock, a non-security crypto asset (such as a payment stablecoin issued by a permitted payment stablecoin issuer under the GENIUS Act), or a tokenized money market fund. Notably, the paired crypto asset need not be a stablecoin.
Each Tokenized NMS Stock must carry the same rights and privileges as the equivalent conventional shares, including the same economic interest, dividends, voting rights, and liquidation rights. For third-party tokenized stock, proxy materials and other issuer communications must also be made available to holders without cost to the issuer or its shareholders. The Order requires equivalence of rights but does not prescribe the custody, transfer agent, entitlement, or reconciliation architecture through which those rights must be delivered.
How the Pilot Works
The Order combines permissioned participation with public blockchain infrastructure. Only participants admitted under standards established by the TSV may trade. The TSV may implement those standards through off-chain screening, on-chain credentials, allowlisted wallet addresses, transfer restrictions embedded in a token, or a combination of those mechanisms. A third party may perform verification functions at the TSV’s direction, but the TSV remains responsible for compliance with the exemption.
At the same time, the smart contracts used by the TSV must be public and auditable, their source code must be publicly available, and they must be deployed on a public, permissionless distributed ledger. The structure is therefore not permissionless DeFi: Access to the securities market is controlled even though the underlying blockchain and smart contracts are publicly accessible.
Trading takes place through AMM liquidity pools rather than a conventional central limit order book. Liquidity providers supply assets to a pool, and the AMM applies its programmed pricing and execution methodology as participants trade against that pool.
The Equity Issuer Has a Meaningful Role
Third-party tokenization does not require issuer sponsorship, but the Order gives the equity issuer an important role before its stock may trade under the exemption.
Before a TSV may offer NMS stock tokenized by an unaffiliated third party, it must give written notice to the issuer and wait at least 30 calendar days. If the issuer submits a timely written objection, the TSV may not rely on the exemption to trade that Tokenized NMS Stock.
The objection is not a general prohibition against tokenization or trading of the issuer’s stock. Instead, it prevents use of this exemption for that tokenized stock. A party seeking to proceed would need another valid legal basis for its activity.
For public companies, this may be one of the Order’s most immediate practical consequences. An issuer receiving notice may need to understand what the token represents, who holds the underlying shares, how the token is backed and reconciled, how voting and distributions will be administered, whether the token could trade differently from the conventional shares, and whether there is a reason to object.
Disclosure, Transparency, Limits, and Oversight
The Order subjects TSVs to a substantial public disclosure, transparency, and oversight regime, together with limits on the scale and operation of the pilot.
Extensive public disclosure. The TSV’s public Notice must include a required disclaimer stating that (i) it is not registered with the Commission, (ii) the Commission has not passed upon the merits or accuracy of the disclosures, (iii) it is not subject to the fair access requirements applicable to registered exchanges and ATSs subject to Rule 301(b)(5) of Regulation ATS and that unfair or discriminatory denials of access are not subject to SEC review, and (iv) it is not subject to Regulation NMS. The Notice must also describe, among other things, its ownership and governance, affiliates, participant categories and eligibility standards, permissioning procedures, eligible assets, tokenization model, trading by the TSV and its affiliates, smart contracts and upgrade controls, trading procedures, hours of operation, market data and oracles, fees, complaint procedures, privacy practices, systems safeguards, clearing and settlement arrangements, service providers, market abuse controls, trading stoppages, and material risks. The Notice must be updated as specified events and operational changes occur.
Public transaction data. A TSV must make a rolling 30 days of transaction data available to the public free of charge, on equal terms, in machine-readable form and updated within 10 minutes. The required information includes the assets traded, price, size, execution time, transaction direction, pool and smart contract information, daily volume, and pool size. A public blockchain record by itself will not necessarily contain all the standardized information required by the Order.
Limits on scale. The pilot limits both the number of stocks traded and the percentage of market-wide trading volume:
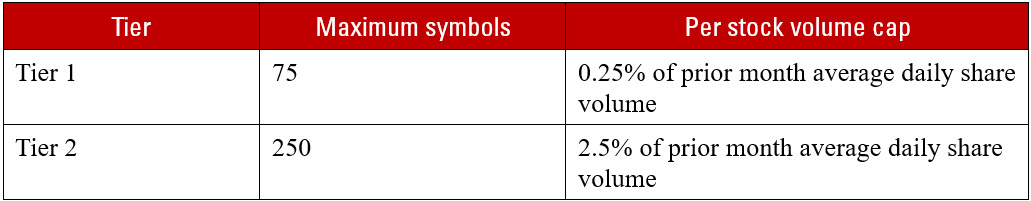
The limits are aggregated across affiliated TSVs. After an initial breach, each subsequent breach of the applicable volume cap requires trading in the affected stock to pause for three months. The Commission describes these restrictions as designed to mitigate potential risks to the broader markets while the Commission considers rulemaking to address the trading of Tokenized NMS Stock.
Trading and operational controls. Trading in Tokenized NMS Stock must cease when trading in the underlying stock is halted or suspended on its primary listing exchange. Significant operational events, including material systems disruptions or intrusions, must be reported to participants and the Commission and remediated promptly.
The TSV may not borrow securities or non-security crypto assets on the TSV, hypothecate or arrange for the hypothecation of those assets, or extend credit to a participant to purchase Tokenized NMS Stock. The exemption therefore does not contemplate a leveraged or margin-based TSV trading model.
Books, records, and SEC access. The TSV must maintain specified records concerning trading, participants, fees, volume, operational events, and its public Notice throughout the exemption and for three years thereafter. Required records must be maintained in the United States and made available to the Commission, and the TSV must consent to SEC examination.
Taken together, these requirements create a bespoke regulatory framework of permissioning, public disclosure, transaction data, operational controls, scale limits, and Commission access in place of many of the requirements that otherwise would accompany operation as a registered exchange or ATS.
Limited Dealer Relief for Liquidity Providers
The Order separately addresses firms that provide proprietary liquidity to TSV pools. The Commission states that supplying liquidity to an AMM does not, standing alone, necessarily make a firm a dealer. Certain activities, however, may present a closer dealer question, including arrangements involving committed capital, pricing, or other characteristics associated with market making.
The Covered Firm Exemption provides limited dealer relief for a qualifying firm’s securities activities in AMM liquidity pools operating under the TSV Exemption. A Covered Firm must trade solely for its own account and may not hold or custody customer assets. It may participate in more than one qualifying TSV, and the exemption does not restrict its non-securities activities.
The Covered Firm must maintain records regarding its ability to maintain sufficient liquid assets to cover potential losses, liquidity supplied, liquidity provision or market-making arrangements, and compensation and incentives. Any public-facing website of the Covered Firm must disclose that it is not registered as a broker-dealer, that it may have liquidity arrangements with TSVs, and that it may receive fees, tokens, or other incentives. It must also notify the SEC regarding its business model, controls, arrangements, compensation, and consent to Commission information requests.
The relief is limited to the covered proprietary liquidity activity. It does not provide general dealer relief, authorize brokerage for customers or custody of customer assets, or exempt securities activities conducted outside qualifying TSV pools.
Unresolved Questions in the Order
The Order addresses its scope and limitations, but as with any pilot framework, certain legal and operational questions remain open for market participants to work through. The following illustrate some of the issues to consider.
Who is the TSV when the venue is operated by multiple participants?
The Order defines a TSV functionally and permits it to consist of an organization, association, or “group of persons.” That accommodates modular market structures in which different parties may operate the pool, front-end, permissioning layer, oracle, tokenizer, or other components, but the Order does not specify how membership in such a group is determined, how responsibility may be allocated among its members, or when a service provider becomes part of the TSV rather than merely a vendor. Questions may also arise from the requirement that the TSV be a U.S. person, because the Order does not specify how that requirement applies where the TSV consists of a group of persons. By contrast, the statutory disqualification condition expressly applies to an organization, association, or person within a group that comprises the TSV. The Order also permits registered entities to participate while requiring registered activity to remain separate from TSV activity, but does not define the degree of operational, personnel, systems, or governance separation required.
How can an unaffiliated third party tokenize stock without creating a separate security?
The Order permits Tokenized NMS Stock created by an unaffiliated third party, while excluding a third party’s own security that merely provides synthetic exposure to the underlying stock. While the Order does not specify the legal structure by which to accomplish this, the SEC staff’s January 2026 tokenization statement identifies a custodial model that appears potentially applicable: a third party, acting as a securities intermediary, holds the underlying security and creates a token representing a security entitlement, so that transfer of the token results in transfer of the entitlement on the securities intermediary’s records. The Staff’s tokenization statement expressly contemplates that the distributed ledger technology (DLT) may itself form part of the intermediary’s system for recording entitlement holders.
A concrete example of that model is found in the SEC Division of Trading and Markets’ December 2025 no action relief for DTC’s tokenization pilot. DTC remains the securities intermediary, the securities remain registered in the name of Cede & Co., and a participant’s existing Article 8 security entitlement is recorded and transferred in tokenized rather than conventional book entry form. DTC uses its LedgerScan system to monitor on-chain transfers and maintain its official records.
Earlier staff guidance under the transfer agent rules is also directionally helpful. In May 2025, the Division of Trading and Markets stated that a registered transfer agent may use DLT as its official Master Securityholder File, or a component of it, without maintaining a separate off-chain duplicate. Although that guidance addresses issuer records rather than records of security entitlements maintained by a third-party securities intermediary, it suggests the staff’s acceptance of the blockchain itself as part of an authoritative securities ownership record and raises the further question whether a TSV may likewise rely directly on an intermediary’s authoritative on-chain entitlement record when executing AMM transactions.
Can a TSV facilitate on-chain settlement without becoming a clearing agency or broker?
The Order expressly contemplates that a TSV may have procedures or arrangements to facilitate clearance and settlement of transactions and requires those arrangements to be disclosed. That raises the question whether the TSV’s role in facilitating settlement would require it to register as a clearing agency, which the Exchange Act defines broadly to include persons acting as intermediaries in securities deliveries or payments, operating certain systems for the central handling of fungible securities, or otherwise permitting or facilitating settlement of securities transactions. The Order expressly limits its relief to the exchange and dealer provisions addressed by the exemptions and requires TSVs to comply with other applicable legal and regulatory requirements.
The statutory definition of “clearing agency” contains various exclusions. For example, SEC staff confirmed in December 2025 that a registered broker-dealer operating an ATS may clear and settle crypto asset securities transactions for its own customers on its internal books without becoming a clearing agency where those functions constitute customary brokerage or dealing activity. That guidance, however, does not necessarily resolve the position of a TSV that is not a dealer and facilitates settlement among independent participants. The Order also requires disclosure of any service providers performing clearance and settlement functions, raising the related question whether such providers themselves may need to register as clearing agencies, rely on an available exclusion, or obtain further exemptive relief.
The Order also specifically provides relief for certain liquidity providers from registering from dealers, but does not expressly address which parties, if any, would be required to register as brokers under Section 3(a)(4) of the Act or provide any exemption from broker registration. Accordingly, parties facilitating or effecting trading on AMM pools through a TSV should still consider their registration obligations when they perform the functions courts and the SEC have associated with brokers, such as solicitation, participation in negotiations, discretionary order handling, taking custody of digital assets, and/or receiving transaction-based compensation for such activities.
What does it mean for trading to be permissioned while the underlying blockchain must be permissionless?
One of the Order’s more distinctive features is its combination of a permissioned securities market with permissionless blockchain infrastructure. The TSV determines who may trade and may enforce eligibility through off-chain screening, allowlisted wallets, or token-level restrictions, but the smart contracts must be public and auditable and deployed on a public, permissionless distributed ledger. The Order generally describes a permissionless ledger as one that anyone can read or write to without authorization.
That requirement may be difficult to apply to institutional or privacy-preserving networks that are decentralized and fully auditable but restrict validator participation, write access, or transaction visibility for confidentiality, compliance, or operational reasons. The Order does not address whether the Commission would be prepared to modify the condition or grant additional relief where comparable transparency and regulatory access are achieved through public code, required transaction reporting, independent auditability, and Commission access. Notably, the Commission expressly invites TSVs to consult with staff about whether a particular ledger meets the requirement and encourages market participants that cannot satisfy a condition to discuss additional relief or modification.
Conclusion
The Innovation Exemption establishes a Commission-level pathway for a defined on-chain market in tokenized public stocks—limited in scope, temporary in duration, and deliberately structured to generate experience that can inform future regulatory action.
The Commission’s comment process, particularly in light of the novel and temporary nature of the Order, offers issuers, market participants, and technology providers a meaningful opportunity to help shape the regulatory framework that may emerge from the Order.
For answers to frequently asked questions about the Innovation Exemption, please visit our related FAQ.
These and any accompanying materials are not legal advice, are not a complete summary of the subject matter, and are subject to the terms of use found at: https://www.pillsburylaw.com/en/terms-of-use.html. We recommend that you obtain separate legal advice.